
Hello, my friends. And welcome to another round of Rapid Fire Listener Questions. And this is your Ask Marco episode on the Passive Real Estate Investing podcast. Well, I hope everyone had a wonderful Christmas weekend. We are at the tail end of the year. This year has just flown by 2022 is just around the corner. And I’m pretty excited about the topics we’re gonna cover into the new year. There is a lot going on with inflation monetary policy, markets that are appreciating some of them highly inflated others offering great opportunity. So we’re gonna have some great guests coming on in the new year. Also, I’ll be talking about some of these topics very soon. And, you know, as I look back on 2021 is just amazing how I was only able to get about half of the projects I wanted to get done, done. And I seem to always overestimate what I can do in the short term, but I always end up underestimating what I can do in the long term.
And I think this is a truism for most people. I think people tend to overestimate what they can do short term, but then if they stick to it, they realize that they can accomplish great things over the years. And so they underestimate what they can do long term. So I think that’s something to think about here as we close up 2021, and as we roll into 2022, you know, set yourself some goals and just, you know, strive to achieve what you want to achieve, but don’t get disappointed if you are not get the momentum that you would like to see short term, because if you stick to it, that momentum compounds on itself and you can accomplish great things over the course of years.
Download your FREE copy of The Ultimate Guide to Passive Real Estate Investing.
If you missed our last episode, be sure to listen to 7 Common Questions Asked of Our Investment Counselors (Part 2)
SUBSCRIBE on iTunes | Stitcher | Podcast Feed
And this is very true for real estate investing as well. A lot of people get started and you know, they have one property, maybe two and things look like they’re just moving along slowly.
But know if you’ve been in real estate here over the last two years, and you’ve seen what rents have done in terms of rent growth and price growth, particularly in many of the markets that we’re in. And that includes the Southern markets like Florida, Texas, any of our Southern state markets. You look back after 12, 24 months, and you’re very impressed by the amount of price growth, the appreciation. In other words, the equity gains that you’ve seen. And it’s just a matter of being patient. Like I’ve said so many times on this show, real estate is a true and tried get rich slow investment. It is not an overnight get rich quick type of deal. So just understand that you gotta stick to it, keep stacking properties as quickly as you can within your capabilities and you’ll accomplish amazing things, amazing things. So let’s take 2, 3, 4 questions here for today’s rapid fire listener question episode and see what we can accomplish. And I have many more of these coming and there are some great questions coming in. So I’m excited to cover more as the episodes roll along.
Okay. The first question comes in from Jasmine, and this is really more of a clarification question. She says, good day, Marco, love your podcast. I have listening for almost a year. I haven’t missed an one episode since well, thank you, Jasmine. In your last episode where you talked about HAI, the Housing Affordability Index, it was mentioned that real versus nominal inflation. I have searched the internet to find concrete, solid information on this knowledge and have a hard time where to find it. What is the difference between real and nominal inflation, not interest rate and how do I find out what is the current real inflation rate right now? Many thanks and keep up the excellent work. Can’t wait to hear my question answered on air smiley face.
Okay. Jasmine. So hopefully it wasn’t a confusing episode because when we talk about real nominal rates, we are generally, and typically talking about inflation. We’re not talking about interest rates, so those are two different things. So let me begin with this, the housing affordability index, what that is, it’s a measure of whether or not a typical family earns enough income to qualify for a mortgage loan on a typical home, either at a national or regional level. That’s the way they measured it. Obviously, if someone’s buying a home, it’s gonna be at the local level in a neighborhood on a street, but it’s just an index. And so, you know, it is what it is. It’s an index just to show affordability based on a region. And that is always based on the most recent housing price, the most recent income data. So that’s what the housing affordability index is all about.
Now, to answer your question specifically about real and nominal rates of inflation. And again, we’re not talking interest rates here, a real value when we’re talking about real rates of anything is one that has been adjusted for inflation. That is typically how it is used. And that enables us to have a comparison of quantities as if the prices of those goods or services have not changed on average over time. So in other words, changes in value in real terms exclude the effect of inflation. So it gives you a real way to compare the value or price of something today versus a time in the past, whether it’s a year or a date in the past, or to make assumptions about what those might be in the future. So all it does is it takes the inflation into consideration. So when we talk about nominal values, those are for example, the current monetary values.
When we talk about real values, we are adjusting for inflation and we’re showing prices or wages at constant prices. So that way we level the playing field and what we’re comparing today, regardless of what that number is, or that dollar amount, we’re comparing that on the same level or same playing field as what that item was, let’s say a year ago or 10 years ago or 30 years ago, if you were able to buy penny candy for a penny 30 years ago, that penny candy today is gonna be 50 cents or a dollar that 50 cents or a dollar is the nominal value, the nominal rate, but the real rate would be something much different. So you gotta understand that when you adjust for inflation, you can keep things in perspective. So that way you have a fair way of comparing how prices have changed. So again, to take that same example, if you bought penny candy for a penny 30 years ago, and today after adjusting for inflation, it’s 2 cents two pennies, well, it’s gone up a hundred percent.
It’s twice as expensive today, even though you know, that you’re paying 50 cents or a dollar in inflated dollar because of inflation, the purchasing power of the dollar has gone down. So you’re paying more for that same item, but in real terms, the purchasing power, if you adjust for that, you’re probably paying the same thing. And so if you’re paying a penny to date in real adjusted dollars, then it hasn’t gone up or down. So it’s one of the those things that can be quick to wrap your head around. But for some people it takes a bit of time to think it through. And the reality is you’re just adjusting for inflation, meaning that the purchasing power of the dollar continually goes down. And as it does, you have to spend more of those dollars to buy the same thing and have that same purchasing power.
So real dollars or real values, give a better guy to what you can actually buy. And it also shows you the opportunity costs you face if you’re evaluating different investment opportunities and adjusting for inflated dollars in the future. And that’s a topic for another day that gets into some more complicated math, but just to kind of round this topic out in terms of real rates and nominal rates of inflation, the Bureau of Labor Statistics that tracks the quote-unquote official inflation rate, you know, they have mentioned that real rate or that nominal rate has been 6.2% so far this year, while that was a statistic from October. So now we’re in December, obviously that’s gonna be adjusted, but you know, they’re saying that 6.2% is the official inflation rate, or sometimes what we call the headline rate of inflation. And that has been the highest level in decades.
In fact, that goes back four decades. So we’re talking 40 years, that’s the highest rate increase in inflation. However, if you calculate the inflation rate using the original methodology from the 1980s, the true inflation rate is actually 6 to 8% points higher than the official statistics indicate. And that means that the real rate of inflation, the way it was originally tracked from the algorithm or the formula that they used back in the 1980s, suggests that the real rate of inflation is somewhere between 12 and 15%. So think about that. And I’ll talk about at this in another episode in more detail, but the reality is is that those numbers, what they tell us, those headline rates are not actually what the real world is showing us in terms of price appreciation. You’re spending more at the pump, more at the grocery store, more on housing and more on whatever else you wanna look at because the real rate of inflation is higher than the inflation rate or the headline rate that they’re talking about. Anyway, I just wanted to throw that in. I know it’s not exactly what you were asking Jasmine, but I appreciate the question. So thank you for that.
Now, the next question, actually, I interesting enough, within a week I had more or less the same question come in from two different people. And I’m just gonna read both their questions, but it’s more or less the same answer. So Travis Wrightson says, Marco, I’ve been listening to the podcast for a while and wanted to get into real estate investing. I have an adult son who also has an interest in real estate, and I have played some of your podcast for him. My son asked me the other day, why don’t we start doing this together? What are the pros and cons of getting into to this with a child? He would eventually inherit everything anyway. So is there a downside to starting my portfolio with him as an LLC member with myself and my wife? And I appreciate your help, Travis.
Okay. So let’s take that. And I’m gonna read you this second question from Josh. Josh just simply writes in saying curious how you would approach investing in real estate with family. I have a few family members interested in pooling capital for investing, but are not sure how to structure the investment. Can we accomplish this outside of an entity with a contract? How would the mortgage work? Okay. So the similarity here is just investing with other people. That’s the common denominator. You guys are both asking about family. Let me focus on that.
So there are four basic ways to hold title to property with another person, regardless of whether they are family or not. The first one is what we refer to as joint tendency and more specifically it’s joint tendency with right of survivorship. This is typically how married couple as well as unmarried couples who want to leave the home or the property to the surviving spouse will hold title.
Now more than two people can hold title this way, but the last person living of that group ends up with 100% of the ownership when they are the sole survivor, the last remaining survivor of that group. So joint tendency just means that you’re holding tendency and title jointly together. So it’s essentially a partnership on title, not by contract, but on title. Then the next method is what we refer to as tenants in common. Now with this structure, each person owns a percentage of the property and the percentages do not have to be equal. So one person can own 99% of the property and the other person can own 1% of the property. Meaning that’s their percentage of ownership on title. One partner can sell their share to another person and each partner can do their own individual, 1031 tax-deferred exchange to avoid capital gains tax.
If they want to invest in other properties, that’s optional, but they are allowed to do a 1031 in the tenants in common set up. So in the situation where one partner passes away, their air share will go to their heirs. If there is probate involved, otherwise they would obviously have to put their ownership into a will and trust. So that way they can direct where that ownership is going to go. So in that scenario, that can mean that a widow ends up owning a share of that home or that property with their spouse or their spouse’s children. As an example, in other words, it can be passed along. So that’s tenants in common, a more common structure is a trust in some states, it makes sense to put your property into a trust. In fact, I would probably argue that in most cases, if not all cases, it’s worth having a trust.
However, I’m talking about a family trust or a master trust, not necessarily just a property trust. However, when we’re talking about a property trust, it just means that the property is put into that trust. And that trust is really just a document that describes who owns the property and who will own the property in case of a death. So it does make sense to have your property in a trust. If you want to transfer title to someone who is not on the deed after your death, and it also avoids probate, you can also leave instructions in your trust about how the property should be handled after your death. For example, a trust and kind, you know, the, a way I describe this is a trust in kind is like a lockbox that you put your property into with a set of instructions. So just think of a trust that way, a lockbox with a set of instructions.
Now, lastly is the LLC. Now this is a common option and this option can be considered both for rental properties as well as personal investments or for that matter. Any asset, very simple to set up, very simple to manage has a lot of protections. However, the liability protection it carries does vary by state. So obviously talk to your asset protection attorney or real estate attorney about that, but the LLC can have as many owners as you want family or otherwise you can include the LLC documents or within those documents, how to sell the property, how sell shares in the LLC, how the sale of those shares will be handled. In other words, it can be a very thorough document if you want it to be about any set of if then conditions. So keep in mind that there’s a lot of power and flexibility in setting up an LLC or limited liability company.
So that is a very common way to have this set up. And then, you know, lastly, I’ll just say that the LLC allows for easy income and losses to flow through to its shareholders or owners or members. So whether you have two members of a family or 20 relatives within that, LLC, you can control how equity and income and losses are handled. But here’s the, the, the one thing about an LLC. If you want to finance the property, you either a need to find a lender that will finance into an LLC. And just as a side note, Norada Real Estate Funding, that’s the only way you can finance the properties that we finance is within an LLC. There are a few exceptions. You could talk to us about that, but generally speaking, most traditional lenders. And currently, if you are financing with conventional financing, you have to put it in the name of one individual or more, but at least one individual, because you are qualifying personally for it.
So you have to have personal income. You have to be able to verify certain things. And of course, more often than not, there’s a personal guarantee attached that because you are, are the one who is backing that qualification, you are signing your name on those lending documents. So those are the four ways to hold title with your family to Josh’s question about, you know, whether you need a contract outside of an entity. Well, I think no matter how you do it, you’re gonna have paperwork involved. So you have a contract of, so if you need a side agreement or an additional contract, you can certainly set that up. That lays out the additional terms of that arrangement and just make sure that is riding on top of the original agreements that you have in place, whether it’s a trust or an LLC or whatnot, as far as how the mortgage works.
Well, somebody needs to qualify, even if it’s in an LLC, somebody at least one individual within that group or that group of family members needs to qualify for that financing. So keep that in mind. Now, a little tip, if you will, if you are, let’s say purchasing this with a family member, let’s say a cousin or an uncle, whatever, if you both qualify individually, there’s no reason for you guys to both qualify on the mortgage, because the disadvantage of doing that is that you are taking up one slot on your credit. If you’re getting conventional financing to get another conventional loan. So you’re allowed up to 10 conventional loans per credit school per individual. And so if you’re both going on the loan together, one of you is taking up a slot that you didn’t need to take up that would allow you to get one more conventional loan on another property at another time.
And so it’s better to keep that free, especially if you guys are planning to buy more than one property together than just do them individually, alternate who’s qualifying for the mortgage. So that’s just a little tip when it comes to conventional financing, but you don’t need to be on there together. And there’s probably no additional liability protections or reasons to be on there together as a group. But just keep in mind that you are taking on some sort of liability exposure. If you are putting your name on that mortgage and you are part of a group, so have the terms and conditions of that relationship that arrangement laid out clearly in your documents, whether it’s in your limited liability company and or some additional agreement that you have as a rider, along with that, and back to Travis, you know, pros and cons of getting into this with your child.
I think it’s a great idea, especially doing it together. Not only are you investing together, but you’re working together, you’re building a bond and you are, are, you know, learning together. It’s a journey in investing. I see really no downside. If you have everything laid out clearly in black and white and everybody knows what they own, what they’re responsible for, what they’re responsibilities are, the liabilities. I think it’s a great idea, but if you have everything clear from the beginning, then hopefully there will be no misunderstandings or arguments later. So I think there’s a lot of pros and few cons. If you lay everything out in a very clear, organized fashion. So Travis, Josh, thank you for those questions. I greatly appreciate it.
Okay. I have time for one more question. So let me grab this one from rich, rich from Illinois, I saw someone had asked about FHA, but that was in 2017. Wow. You’ve been listening for a long time. The possibility of putting only 3% down in order to get a four flat or fourplex started to seem like a good idea. I understand that you qualify by the rent of three units, carrying the mortgage. You are required to live in the fourth. Do you, you have any insight into this program and or experience using it?
Okay. So this is a great question, cuz some people like to get started by using an FHA loan, which is easier to qualify for, has a much lower down payment. You typically only do this one time once at a time and you are not exactly qualifying by the other three. As you mentioned in carrying the mortgage, you are still qualifying before you own this property. So again, talk to your mortgage lender, loan officer, to get more specifics about the qualification criteria and what is, and isn’t included in your income to qualify for that mortgage, which is part of the debt to income cash calculation.
But to start from the beginning, an FHA loan is essentially a mortgage that is guaranteed by the government. An FHA loan is designed for you as the borrower in situations where you have lower than average credit scores and maybe a lack of funds for a larger down payment, larger compared to conventional financing, which is typically 20% or 25%, depending on how many mortgages you have. So an FHA loan is a cheaper and easier loan to qualify for, but it has some rules and restrictions. So FHA loans, for the most part, they’re restricted to buyers who intend to use that property that they’re purchasing as their primary residence. So that means that you can’t use an FHA loan for a second home or a rental property or a vacation home or an investment property. However, there are some exceptions and a few ways to get around this basic but critical rule.
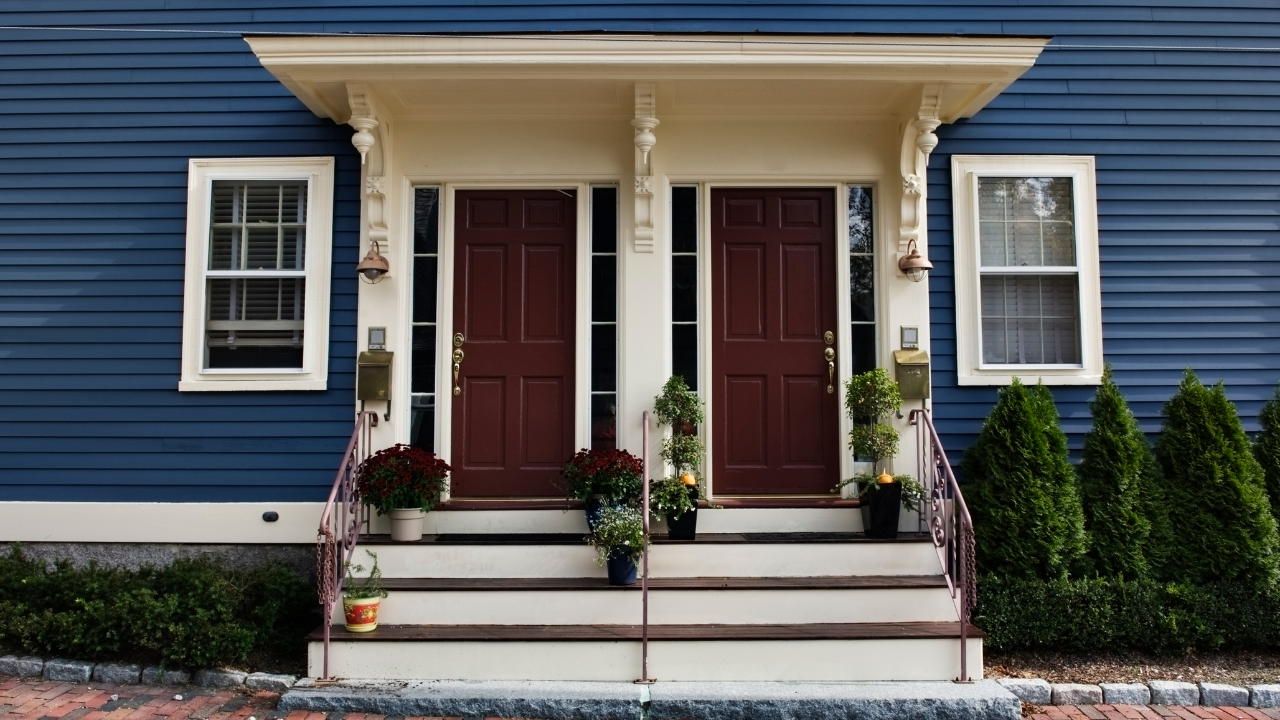
And the one way to use the FHA loan to buy an income property is to purchase a multi-unit dwelling, which is exactly what you’re talking about here in your question, rich. So a four flat or fourplex, however you wanna describe it is a multi-unit dwelling. It’s considered a residential multi-unit dwelling and FHA allows you to buy a property up to four units provided that one is occupied by you. There’s no upper limit to the size of the loan. And in this way, an owner like yourself is able to buy it live in one unit, make that an owner occupied property for yourself, which qualifies for FHA. And then you can rent out the other unit to whether it’s one, two or three other units and use that income as the income from your property, which basically subsidizes your living at that property. And if you buy right in the right areas, you may have positive cash flow, which is great.
So now you’re actually living free and making some money through the cash flow of the property. So that’s essentially it. Now one key thing to know is a lot of times people will invest in real estate using an FHA loan and then their goal or strategy later is to refinance that into a fixed rate, 30 year conventional mortgage. If you plan to do that, then you have to understand that there is a minimum of 210 is that have to pass. Since you originally closed on that FHA loan before you can actually do a refinance, which is not bad, that’s less than a year. And you also have to have made at least six monthly payments, which shouldn’t be an issue unless you’re completely cash strapped and you’re not getting rents from the other units. And lastly, if you have had your FHA loan for less than a year, you cannot have had any payments overdue for more than 30 days.
So these are very straightforward, common sense. Things just pay on time. Don’t be late, make all your monthly payments on time and do that for at least six months. And then after 210 days, you can refinance if you want to. And if it makes sense, I mean, again, it’s a math question. Investing is a lot about math and rates of return. So Rich, thank you for the question. I hope that helps. I’m gonna cut it off here. I’ve got some other things I gotta take care of. So after 26 minutes, I think we’ve covered enough, but I’ll get more listener questions out here soon.
So thank you for sending those questions in. If you have any questions in mind, just send them over to me. Go to the passive realestateinvesting.com website, click Ask Marco. I will be happy to take on as many as I can remember to subscribe to the show. If you haven’t done so already, it’s just one click of, of a button and it takes you all of two seconds. Share the show with your friends, family, and neighbors, any like-minded individual. And of course I read all the ratings and reviews that you leave us on iTunes and wherever else. So thank you for that. And that is it for today. Thank you for listening. Have a wonderful new year and we will see you soon.
Download your FREE copy of: The Ultimate Guide to Passive Real Estate Investing.
Get your FREE coffee mug by leaving us a Rating and Review on iTunes. Here’s how.
See our available Turnkey Cash-Flow Rental Properties.
Please give us a RATING & REVIEW (Thank you!)